Latin America's Tech Industry: MercadoLibre, Nubank, and the Fintech Continent
Abstract
Latin America’s recent technology industry is largely about financial exclusion and the companies that set out to fix it. It has a prehistory that the fintech decade tends to hide: a Ferranti Mercury in Buenos Aires in 1961, a Brazilian-built minicomputer in 1972 and a fifteen-year Brazilian import ban on foreign computers that ended in a trade war with the United States. In a region of 650 million people, about half of all adults had no bank account in 2014, inflation routinely destroyed savings, and sending money home from abroad was expensive. MercadoLibre built the region’s dominant e-commerce and payments platform starting in 1999. Nubank, founded in 2013, became the largest digital bank outside Asia, and Brazil’s central bank built the instant-payment system Pix. Rappi, Clip, Kavak, and dozens of others followed. Venture capital from SoftBank, Tiger Global, Sequoia, and Andreessen Horowitz peaked in 2021 and fell back when interest rates rose; the structural problems (currency devaluation, regulatory fragmentation, infrastructure gaps) remained.
The University Machines, 1957–1972
Latin American inventors had been filing calculating-machine patents long before any computer arrived. In the US patent records alone there are José Villa’s proportional dividers from Medellín (1880), a multiplying and dividing pen by José Herran y Bolado of Aguascalientes (1891), typewriter keyboards by Juan Vidal of Havana (1900s), two cipher machines by Ramón Guzmán of Tegucigalpa (1914 and 1917), a coding device by João Pinto Pessôa of Rio de Janeiro (1923) and an electric digital calculator by Meade Zimmer, an American at the national observatory in Córdoba, Argentina (patented 1934). Punched cards came early too. Valentim Bouças opened Serviços Hollerith in Rio de Janeiro in 1917 to import and rent the machines of the company that became IBM, so successfully that a Brazilian payslip is still called a holerite; IBM opened its first Brazilian factory in 1939.
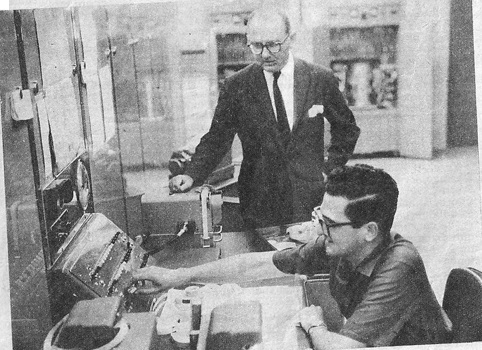
The region’s first computers were bought, not built, and the two earliest are still arguing about which came first. The São Paulo state government installed a punched-card Univac 120 in 1957 for its water and sewerage department. Mexico’s UNAM counts its IBM 650 as the first in Latin America: the engineer Sergio Beltrán López had seen IBM machines in California while studying the geology under Mexico City, persuaded the university to buy one, and the machine started work on 8 June 1958 in the basement of the Faculty of Sciences, with the Centro de Cálculo Electrónico growing around it. São Paulo’s machine was earlier; UNAM’s was the first at a university and the first with a research group attached. Brazil followed with an IBM RAMAC for a São Paulo company in 1959, a Univac 1105 for the 1960 census in Rio and a Burroughs 205 at PUC-Rio, inaugurated by President Juscelino Kubitschek and Cardinal Montini, the future Pope Paul VI.
Argentina’s entry was the most ambitious. Manuel Sadosky, a mathematician at the University of Buenos Aires, pushed an international tender through in 1959, and the Instituto de Cálculo bought a Ferranti Mercury for £152,099. It arrived on 24 November 1960, filled eighteen metres of cabinets in Pabellón I of the Ciudad Universitaria and entered service in January 1961. The staff named it Clementina after the tune in Ferranti’s sample programs. Cecilia Berdichevsky was among its first programmers; Wilfred Durán and four students, Liana Lew, Noemí García, Ana Cristina Zoltan and Clarisa Cortés, wrote COMIC, the first Argentine programming language, for it. On 29 July 1966, a month after the military coup, police cleared the faculty with truncheons in what became known as the Noche de los Bastones Largos. Sadosky and most of the institute went into exile, and Clementina ran on with a shrinking staff until spare parts ran out in mid-1971 (see SADIO Argentina for Sadosky’s later career).
Brazil’s home-built computers came out of classrooms. Students at the army engineering school IME built Lourinha between 1958 and 1960, with Helmut Schreyer, Zuse’s former partner, among their teachers; four students of the air-force institute ITA in São José dos Campos built the transistorised Zezinho in 1961, a teaching machine on a panel two metres wide that was soon dismantled. The one that led to an industry started in 1971, when Glen Langdon Jr., an American professor who had worked at IBM Brazil, proposed that the Digital Systems Laboratory of the Escola Politécnica at the University of São Paulo build its own machine as a course project. Eighteen graduate students did: Patinho Feio (“Ugly Duckling”), an eight-bit computer of 450 integrated circuits on 45 boards, weighing 100 kilos, was presented on 24 July 1972 before the state governor and the university rector. A photographer stepped on its power cable during the ceremony and the machine took too long to restart. It worked afterwards. The design led to the G-10, commissioned by the Brazilian Navy from USP and PUC-Rio, and from there to the MC 500, sold by Cobra Computadores, founded on 18 July 1974 by the Navy, a state bank and the British firm Ferranti; it was the first Brazilian commercial computer; members of the Patinho Feio team founded Scopus Tecnologia in 1975. Chile’s contribution in the same years was a control room rather than a computer: Project Cybersyn, 1971 to 1973.
Dead End: Brazil’s Market Reserve
Cobra’s founding was the start of the largest computing-policy experiment in the region. Brazil’s military government classified computing as strategic in the early 1970s, first under the coordinating body CAPRE and from 1979 under the Secretaria Especial de Informática (SEI), staffed by officers linked to the intelligence service. The policy was a reserva de mercado: foreign firms were kept out of minicomputers and microcomputers so that Brazilian companies could learn to build them. Congress wrote it into law on 29 October 1984 as Lei 7.232, the Informatics Law, with an eight-year term. Severo Gomes and Cristina Tavares carried the bill; Roberto Campos challenged it as unconstitutional and lost. The manufacturers’ association ABICOMP, the data-processing union and the Brazilian Computer Society all lobbied for it.
The results were domestic firms (Cobra, Itautec, Scopus, Elebra, Prológica from 1976, Microdigital from 1981, whose TK90X copied the ZX Spectrum) and licensees such as Labo Eletrônica, which built Nixdorf systems from 1978 to 1989, turning out machines a generation behind the imports they replaced, at higher prices, and a grey market in smuggled PCs. Washington opened a Section 301 case, and on 13 November 1987 President Reagan announced sanctions against Brazil, tariffs meant to offset an estimated US$105 million in lost sales of American companies, after Brazil refused to license an American software product because a domestic equivalent existed. The 1991 revision of the law redefined “national company” to let foreign capital back in, and the reserve expired on schedule in October 1992. Brazil kept a computing profession and a research community that had grown up on its own machines. It did not keep a computer industry: within a few years the domestic manufacturers were assemblers of imported designs. The lesson repeated across the region was that a protected market could produce engineers but not a product anyone outside it wanted.
The Infrastructure of Exclusion
In 2014 the World Bank’s Global Findex survey found that only about 51% of adults in Latin America and the Caribbean had an account at a financial institution, up from 39% in 2011. The reasons were structural: bank branches concentrated in cities, minimum balance requirements that excluded low-income accounts, identification requirements that many informal workers could not satisfy, and banking fees that consumed a meaningful fraction of small transactions. The formal financial system had been designed for and by the urban middle and upper classes; the majority of the population used cash for everything.
Cross-border remittances (the money that migrant workers sent home to families) cost on average about 7.5% of the amount sent worldwide in 2015, according to the World Bank’s price database. Mexico alone received about $25 billion a year in remittances, so the fees, collected by banks and money-transfer firms such as Western Union, were a large drain on poor households.
Small businesses paid high card-processing fees, and card terminals cost more than many merchants could afford, so most transactions were in cash. These conditions explain why fintech dominated the region’s technology output.
MercadoLibre
Marcos Galperin was a Stanford MBA student in 1999 when he drafted a business plan for an online marketplace. He pitched it to private-equity investor John Muse (of Hicks, Muse, Tate & Furst), a guest speaker at Stanford whom Galperin offered to drive to the airport, and secured an initial investment. He launched MercadoLibre (Spanish for “free market”) in Argentina in August 1999, shortly after returning from Stanford.
The Argentine peso was pegged to the dollar under the convertibility plan; Argentine internet penetration was minimal; e-commerce infrastructure (logistics, payments, consumer trust) did not exist. Galperin built the marketplace anyway, expanding into Brazil, Mexico, Colombia, Venezuela, and eventually most of Latin America.
MercadoLibre survived the Argentine crisis of 2001–2002 (frozen bank accounts, riots in which dozens died, and a peso that lost about 70% of its value) through careful cash management and a September 2001 deal with eBay, which took a 19.5% stake. It then built MercadoPago (2003), a PayPal-like system that let buyers and sellers transact without sharing bank account or card details. Galperin himself moved to Montevideo, Uruguay, around 2020.
MercadoPago solved a trust problem specific to Latin America: consumers would not enter credit card details on websites they did not trust, and the region lacked the institutional infrastructure of escrow services, consumer protection laws, and bank dispute resolution that made US e-commerce workable. MercadoPago held funds in escrow until buyers confirmed receipt; sellers received payment only after delivery confirmation. The system enabled e-commerce by removing the trust requirement from individual transactions.
In 2023 MercadoLibre had revenues of about $14.5 billion, of which $6.3 billion came from its fintech business, and almost 85 million buyers on its marketplace; it was among the most valuable companies operating in Latin America. MercadoPago had grown into a financial-services platform offering credit, insurance, and investment products, often to users with no prior bank relationship, using their transaction history in place of a credit score.
Nubank
David Vélez, a Colombian venture capitalist, moved to São Paulo in 2012 for Sequoia Capital and found opening a bank account slow, bureaucratic and expensive. He concluded that Brazil’s concentrated banking market left room for a digital bank with no branches and no legacy technology.
He founded Nubank in São Paulo in 2013 with co-founders Cristina Junqueira and Edward Wible. The first product was a purple credit card with no annual fee, managed entirely through a mobile app. The application process was entirely digital; approval took minutes rather than weeks. The interest rate was still high (Brazilian interest rates were and remain among the world’s highest, reflecting the central bank’s inflation-targeting regime and the cost structure of Brazil’s banking system), but transparent and consistently lower than incumbent alternatives.
Nubank grew through word of mouth and an invitation-only waiting list. By the end of 2021 it had more than 50 million customers across Brazil, Mexico, and Colombia, and its listing on the New York Stock Exchange in December 2021 valued it at about $41 billion. It ended 2023 with nearly 94 million customers, about 88 million of them in Brazil, more than half of the country’s adults, and in May 2024 passed 100 million, the first digital bank outside Asia to do so.
Why Brazil?
Brazil’s banking sector was (and remains) among the most concentrated and profitable in the world. Five banks (Itaú, Bradesco, Caixa, Banco do Brasil, Santander Brasil) held about 80% of banking assets. The Banco Central do Brasil later encouraged fintech entry through a regulatory sandbox and mandatory open banking, introduced from 2021.
Pix
The most widely used financial technology in Latin America came from a central bank.
Pix, launched by the Banco Central do Brasil on November 16, 2020, was an instant payment infrastructure that allowed any Brazilian with a bank account or fintech account to transfer money to any other Brazilian instantly, 24 hours a day, seven days a week, at no cost for individuals. Banks and fintechs were required by regulation to implement Pix if they had over 500,000 customer accounts.
Adoption was fast: within about eighteen months more than 100 million Brazilians had registered Pix keys. By 2023, Pix processed over 3 billion transactions per month, surpassing credit cards as Brazil’s most-used payment method. The cost of transferring money between Brazilian accounts, which had previously ranged from R$5 to R$20 per transaction, dropped to zero.
Private fintechs had spent a decade trying to cut the cost and friction of payments; the Banco Central did it in eighteen months by mandating a shared infrastructure.
The Regional Ecosystem: Colombia, Mexico, Chile
Colombia produced Rappi, founded in 2015 by Simón Borrero, Sebastián Mejía, and Felipe Villamarín. Rappi began as a delivery app and expanded into payments, financial services, and eventually a super-app model serving Colombia, Brazil, Mexico, Argentina, and Peru. It became Colombia’s first unicorn in 2018, and in April 2019 SoftBank invested $1 billion at a reported valuation of about $3.5 billion.
Mexico produced Clip (card readers for small merchants, 2012), Kavak (used car marketplace, 2016), and Konfio (SME lending, 2013). Mexico City became the region’s second major tech hub after São Paulo.
Chile (with smaller population but higher GDP per capita and better institutional quality) produced NotCo (AI-generated plant-based food), Cornershop (grocery delivery, acquired by Uber), and Buk (HR software). Chile’s startup ecosystem benefited from government support through CORFO (the state development agency) and its Start-Up Chile programme (2010).
Dead End: Currency, Regulation, and the Funding Cliff
Venture capital invested in Latin America peaked in 2021 at roughly $16 to $20 billion, depending on the count, driven by SoftBank’s $5 billion Latin America funds, Tiger Global, and a wave of US-based funds entering the region. As global interest rates rose in 2022 and technology valuations contracted, Latin American startups faced a funding environment that had changed faster than their businesses could adapt.
The structural challenges that had always existed became acute:
Currency risk: Companies raising dollars, spending in local currencies, and earning in local currencies faced existential exposure when the Brazilian real, Argentine peso, and Colombian peso all depreciated significantly against the dollar in 2022–2023. Argentine inflation passed 100% a year in 2023.
Regulatory fragmentation: Each Latin American country has different financial regulations, tax codes, labor laws, and data protection requirements. A company operating in Brazil, Mexico, Colombia, Argentina, and Chile effectively operates in five different regulatory environments requiring five different compliance operations. The cost overhead limited which companies could scale pan-regionally.
Logistics infrastructure: Latin America’s physical infrastructure (roads, postal systems, last-mile delivery) remained poor outside major cities. E-commerce companies that worked efficiently in São Paulo and Mexico City faced structural limitations outside them. MercadoLibre invested heavily in its own logistics network (Mercado Envíos) for this reason; few others could afford equivalent investment.
📚 Sources
- Clementina (computadora) — Wikipedia (Spanish)
- Cecilia Berdichevsky — Wikipedia
- “Hace 60 años la UNAM puso en marcha la primera computadora en AL” — Gaceta UNAM
- Heinz Nixdorf MuseumsForum blog, “Computer in Brasilien” (6 September 2022) (Bouças and Serviços Hollerith, the 1959 and 1960 imports, Lourinha and Zezinho, Cobra’s founders, Prológica, Microdigital, Labo)
- Heinz Nixdorf MuseumsForum blog, “Erfinde, Amigo! – Patente aus Lateinamerika” (26 May 2026) (the US patents filed from Latin America, 1880 to 1934)
- “1957: o primeiro computador chegava ao Brasil” — Embarcados
- “The legacy of the ugly duckling” — Pesquisa FAPESP
- Patinho Feio — Wikipedia
- Ronald Reagan: “Statement on Trade Sanctions Against Brazil” (13 November 1987), American Presidency Project
- Política Nacional de Informática — Wikipedia (Portuguese)
- Schwartzman, Simon: “High Technology and Self-Reliance: Brazil Enters the Computer Age” (1985)
- Nubank — Wikipedia
- MercadoLibre: Annual Report 2023
- Banco Central do Brasil: Pix Statistics and Implementation Reports
- LAVCA (Latin American Venture Capital Association): Industry Data 2021–2023
- World Bank: Global Findex Database 2021 — Financial Inclusion in Latin America
- The Economist: “Latin America’s technology boom” (June 2021)
- Brookings: “Financial inclusion in Latin America: Regulatory trends and market opportunities” (2015) (Findex 2014: 51% account ownership)
- MercadoLibre, Form 10-K for fiscal 2023
- “Nubank surpasses 100 million customers”, Nubank (May 2024)
- “SoftBank makes a huge bet on Latin America”, TechCrunch (30 April 2019)
- “Rappi becomes Latin America’s latest unicorn”, Endeavor (2018)